Category: Tax Updates

Stay updated with the latest tax news, income tax updates, GST changes and financial regulations from India and around the world. Read expert insights on tax rules, government policies, filing updates, compliance, deductions and important changes that impact individuals and businesses on Indian FastTrack.

  • Fixed Deposit Interest Rate Comparison: सितंबर 2026 में किस बैंक की FD सबसे ज्यादा ब्याज दे रही?

    Fixed Deposit Interest Rate Comparison: सितंबर 2026 में किस बैंक की FD सबसे ज्यादा ब्याज दे रही?

    Best Bank for FD: सितंबर 2026 में SBI, HDFC, ICICI और Small Finance Banks की FD rates की तुलना करें। जानें 1, 3 और 5 साल की FD, senior citizen rate, tax, DICGC insurance और premature withdrawal के नियम।

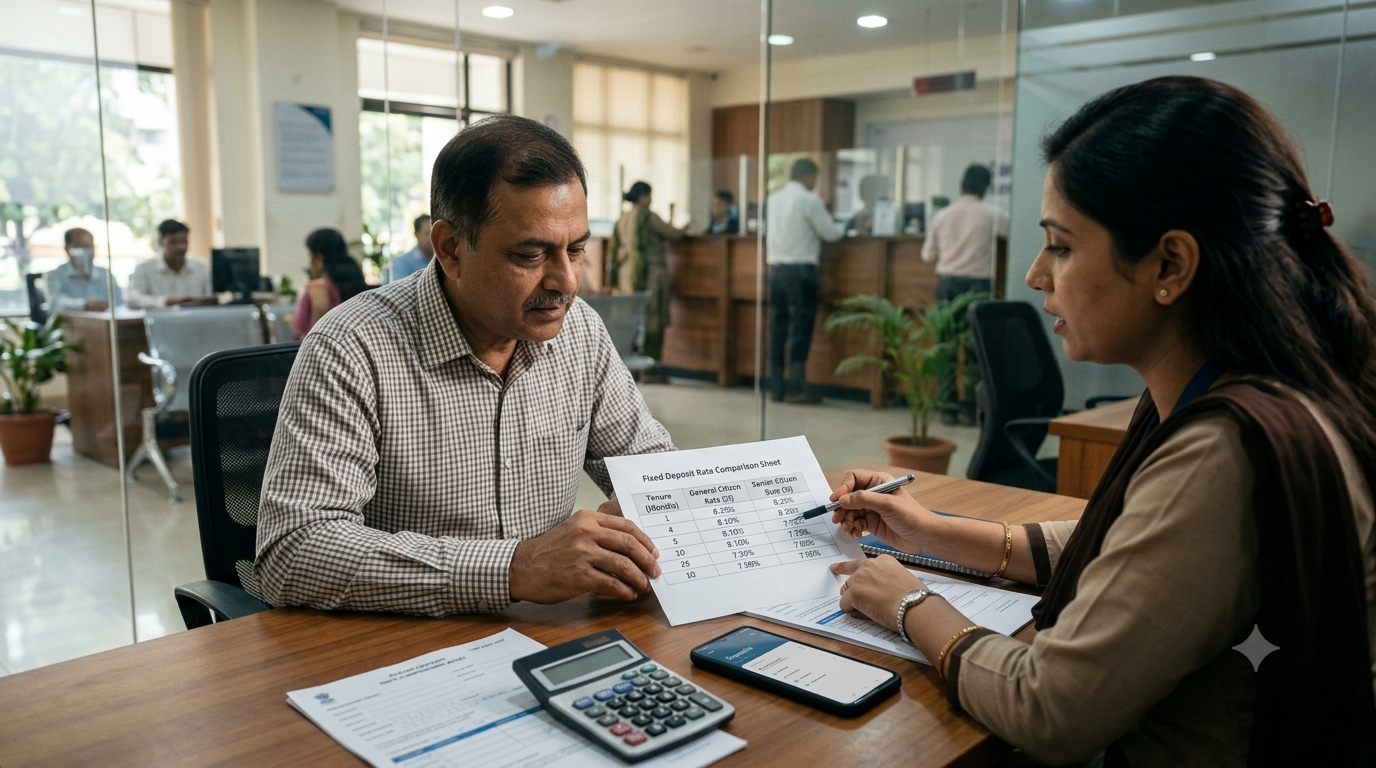
    Fixed Deposit Interest Rate Comparison: अगर आप FD कराने की तैयारी कर रहे हैं और कौन सी बैंक फिक्स डिपॉजिट पर ज्यादा ब्याज दे रहा है? जैसे सवाल के जवाब खोज रहे हैं, तो केवल सबसे ज्यादा ब्याज दर देखना पर्याप्त नहीं है। सितंबर 2026 में कुछ Small Finance Banks चुनिंदा अवधि की FD पर 8% से ज्यादा ब्याज दे रहे हैं, जबकि बड़े सरकारी और प्राइवेट बैंकों की दरें अलग हैं। सबसे ज्यादा FD rate किस अवधि पर मिल रही है, senior citizens को कितना फायदा है और FD कराने से पहले DICGC insurance, tax तथा premature withdrawal जैसे नियमों को समझना भी जरूरी है।

    सितंबर 2026 में सबसे ज्यादा FD ब्याज कहां मिल रहा है?

    16 सितंबर 2026 के उपलब्ध comparative data के मुताबिक Suryoday Small Finance Bank ने चुनिंदा tenure में 8.25% तक की FD दर दी। Equitas Small Finance Bank, ESAF Small Finance Bank, Jana Small Finance Bank और Shivalik Small Finance Bank की दरें भी चुनिंदा अवधि में 8% तक पहुंचीं।

    हालांकि यहां सबसे महत्वपूर्ण बात यह है कि 8.25% को सभी FD अवधि की दर नहीं समझना चाहिए। उदाहरण के लिए Suryoday की सबसे ऊंची दर एक खास 5-year tenure से जुड़ी थी, जबकि दूसरी अवधि में दर अलग थी। इसी तरह Jana Small Finance Bank की 8% दर 2 से 3 साल की अवधि के लिए थी।

    यानी किसी बैंक की FD को चुनने से पहले ब्याज दर के साथ tenure भी देखना जरूरी है।

    चुनिंदा Small Finance Banks की FD दरें

    बैंकअधिकतम दरकिस अवधि पर
    Suryoday Small Finance Bank8.25%5 साल
    Equitas Small Finance Bank8.00%चुनिंदा अवधि
    ESAF Small Finance Bank8.00%800 दिन
    Jana Small Finance Bank8.00%2–3 साल
    Shivalik Small Finance Bank8.00%चुनिंदा अवधि

    दरें उपलब्ध 16 सितंबर 2026 के comparative data के आधार पर हैं। FD कराने से पहले संबंधित बैंक की वर्तमान दर और शर्तें जरूर जांचें।

    SBI, HDFC और दूसरे बड़े बैंकों की FD दरों से तुलना क्यों जरूरी है?

    FD चुनने वाला ग्राहक अक्सर सबसे पहले SBI, HDFC Bank, ICICI Bank और Axis Bank जैसे बड़े बैंकों की दर देखता है। लेकिन Small Finance Banks की कुछ special-tenure FD दरें इन बड़े बैंकों की सामान्य retail FD दरों से ज्यादा हो सकती हैं।

    उदाहरण के लिए HDFC Bank की आधिकारिक rate page पर 22 सितंबर 2026 के लिए अलग-अलग deposit slabs और tenures की दरें दी गई हैं। इससे यह भी स्पष्ट होता है कि FD rate केवल बैंक के नाम से तय नहीं होती, बल्कि राशि, अवधि और FD के प्रकार के अनुसार बदल सकती है।

    best-bank-for-fixed-deposit-interest-rate

    इसलिए “कौन सा बैंक सबसे अच्छा है?” का जवाब केवल एक highest-rate number देखकर देना सही नहीं होगा।

    1 साल, 3 साल या 5 साल—किस FD में कितना फर्क पड़ता है?

    FD की ब्याज दर tenure के साथ बदलती है। हालिया comparison में कई Small Finance Banks की 1-year और 3-year rates में काफी अंतर दिखाई देता है। उदाहरण के लिए Jana Small Finance Bank की उपलब्ध दर 1-year tenure के लिए 7% और 3-year tenure के लिए 8% थी, जबकि 5-year tenure पर यह 7.77% थी।

    इसका मतलब है कि अगर आपको केवल एक साल के लिए पैसा रखना है, तो 5-year FD की headline rate देखकर बैंक चुनना उपयोगी नहीं होगा।

    FD चुनते समय पहले अपनी जरूरत की अवधि तय करें और फिर उसी अवधि की दरों की तुलना करें।

    501 दिन की FD पर भी मिल सकता है ज्यादा ब्याज

    FD comparison में केवल 1, 2, 3 और 5 साल की अवधि देखना भी पर्याप्त नहीं है। कुछ बैंक special tenure FD लेकर आते हैं।

    Unity Small Finance Bank की उपलब्ध revised rates में 501-day FD पर सामान्य ग्राहकों के लिए 8% और senior citizens के लिए 8.50% की दर बताई गई है। बैंक ने premature withdrawal पर 1% penalty की शर्त भी बताई है।

    यही वजह है कि FD की तुलना करते समय special tenure को भी देखना चाहिए।

    Senior Citizens के लिए FD में कितना ज्यादा ब्याज?

    Senior citizens को कई बैंक सामान्य ग्राहकों की तुलना में अतिरिक्त ब्याज देते हैं। हालिया market comparisons में कुछ Small Finance Banks की senior-citizen rates 8% से ऊपर रही हैं।

    कुछ special-tenure products में senior citizens के लिए दर 8.50% तक पहुंची है। Unity Small Finance Bank की 501-day FD इसका एक उदाहरण है।

    इसलिए 60 वर्ष या उससे अधिक उम्र के निवेशक को सामान्य FD rate के बजाय senior citizen FD rate अलग से देखनी चाहिए।

    Income Tax Department के अनुसार tax purposes के लिए 60 वर्ष या उससे अधिक लेकिन 80 वर्ष से कम उम्र का resident individual senior citizen और 80 वर्ष या उससे अधिक उम्र का व्यक्ति super senior citizen माना जाता है।

    FD पर 8.50% ब्याज दिख रहा है तो क्या पूरा पैसा सुरक्षित है?

    यहां FD rate के साथ deposit insurance समझना बेहद जरूरी है।

    DICGC के अनुसार eligible bank deposits में एक depositor को एक bank में, एक ही right और capacity में principal और interest मिलाकर अधिकतम ₹5 लाख तक insurance cover मिलता है। एक ही बैंक की अलग-अलग branches में रखे deposits को insurance calculation के लिए जोड़ा जाता है।

    उदाहरण के लिए, केवल अलग-अलग branches में FD खोलने से insurance limit अलग-अलग ₹5 लाख नहीं हो जाती।

    इसलिए बड़ी राशि की FD करते समय केवल ब्याज दर नहीं, बल्कि deposit insurance structure को भी समझना जरूरी है।

    FD तोड़ने पर क्या होगा?

    अगर FD को maturity से पहले बंद किया जाता है, तो बैंक की applicable premature withdrawal policy लागू होती है। इसमें ब्याज की गणना अलग दर पर हो सकती है और penalty भी लग सकती है।

    उदाहरण के तौर पर Unity Small Finance Bank ने अपनी 501-day FD के लिए premature withdrawal पर 1% penalty का उल्लेख किया है।

    इसलिए FD खोलने से पहले यह जरूर देखें:

    • premature withdrawal allowed है या नहीं
    • penalty कितनी है
    • ब्याज किस rate से calculate होगा
    • partial withdrawal की सुविधा है या नहीं
    • auto-renewal की शर्त क्या है

    FD के ब्याज पर टैक्स लगता है?

    FD का interest सामान्य तौर पर taxable income के दायरे में आता है। इसलिए केवल FD rate देखकर वास्तविक return का अंदाजा नहीं लगाना चाहिए।

    Senior citizens के लिए Income Tax Department के अनुसार Section 80TTB के तहत eligible deposit interest पर ₹50,000 तक deduction उपलब्ध है। इसमें bank और post office के साथ cooperative banks के deposits से मिलने वाला interest भी शामिल है।

    Income Tax Department यह भी बताता है कि senior citizen को bank, post office या cooperative bank द्वारा interest payment पर ₹50,000 तक की सीमा के भीतर TDS नहीं काटा जाता। TDS नहीं कटना और interest का tax-free होना एक ही बात नहीं है।

    Tax-saving FD और सामान्य FD में क्या अंतर है?

    अगर आपका उद्देश्य tax saving है, तो सामान्य FD और tax-saving FD को एक जैसा नहीं समझना चाहिए।

    Tax-saving FD में आम तौर पर 5 साल का lock-in होता है और eligible investment पर Section 80C के तहत tax benefit मिल सकता है। लेकिन इसकी liquidity सामान्य FD जैसी नहीं होती।

    इसलिए अगर आपको अगले एक-दो साल में पैसे की जरूरत पड़ सकती है, तो केवल tax benefit देखकर ऐसी FD चुनना उचित नहीं होगा।

    Bank FD या Post Office Time Deposit?

    FD की तुलना केवल banks के बीच करने से पूरी तस्वीर नहीं मिलती। Post Office Time Deposit भी conservative savers के लिए एक अलग विकल्प है।

    इसलिए final decision से पहले इन बातों की तुलना की जा सकती है:

    Bank FD: बैंक की FD rate, tenure, premature withdrawal rules और applicable deposit insurance देखें।

    Post Office Time Deposit: संबंधित अवधि की सरकारी small-savings rate और उसके नियम देखें।

    इस comparison में सिर्फ headline interest rate नहीं, बल्कि tenure और liquidity को समान आधार पर देखना जरूरी है।

    अगर ₹5 लाख FD में लगाएं तो क्या देखें?

    मान लीजिए आपके पास ₹5 लाख हैं। दो FD में केवल 1 percentage point का rate difference दिखाई देता है। तब भी actual maturity amount में अंतर आएगा।

    लेकिन यहां एक महत्वपूर्ण बात है: FD का final maturity amount compounding frequency, payout option, tenure और bank की calculation methodology पर निर्भर कर सकता है।

    इसलिए किसी भी FD में ₹5 लाख लगाने से पहले बैंक के official maturity calculator या deposit terms से final maturity amount verify करना बेहतर है।

    FD चुनते समय ये 7 चीजें जरूर देखें

    1. Interest rate — केवल highest rate नहीं, अपने tenure की rate देखें।
    2. Tenure — 1, 2, 3, 5 साल या special tenure में क्या जरूरत है।
    3. Premature withdrawal — FD समय से पहले तोड़ने पर penalty और interest rule।
    4. Senior citizen benefit — लागू होने पर अतिरिक्त ब्याज।
    5. Tax impact — interest income पर tax और TDS rules।
    6. DICGC cover — eligible deposits पर ₹5 लाख तक insurance limit।
    7. Liquidity — पैसा बीच में चाहिए तो कौन-सी FD सुविधा उपलब्ध है।

    तो कौन सा बैंक FD के लिए सबसे अच्छा है?

    इसका जवाब केवल एक बैंक के नाम से नहीं दिया जा सकता। सितंबर 2026 के उपलब्ध data में अलग-अलग banks की highest FD rates अलग-अलग tenures पर हैं। Suryoday Small Finance Bank की 8.25% दर 5-year tenure से जुड़ी थी, जबकि Jana Small Finance Bank की 8% दर 2–3 साल की अवधि पर थी। Unity Small Finance Bank ने 501-day FD पर सामान्य ग्राहकों के लिए 8% और senior citizens के लिए 8.50% की दर बताई है।

    इसलिए FD चुनने का तरीका यह होना चाहिए:

    पहले तय करें पैसा कितने समय के लिए रखना है → फिर उसी tenure की rates compare करें → senior citizen benefit देखें → premature withdrawal और tax rules देखें → अंत में deposit insurance और बैंक की applicable terms जांचें।

    यानी “सबसे ज्यादा FD rate” और “आपके लिए सही FD” हमेशा एक ही चीज नहीं होती।

    जरूरी नोट

    FD interest rates बैंक द्वारा समय-समय पर बदली जा सकती हैं। ऊपर दिए गए rates संबंधित उपलब्ध तारीखों के market/official data पर आधारित हैं। FD खोलने से पहले संबंधित बैंक की official website या branch से उस दिन लागू interest rate, tenure, premature withdrawal, tax और अन्य terms की पुष्टि जरूर करें।
  • Petrol Pump UPI Rule: ₹2,000 से ज्यादा के भुगतान पर बदलेंगे नियम, जानिए ग्राहकों पर क्या होगा असर

    Petrol Pump UPI Rule: ₹2,000 से ज्यादा के भुगतान पर बदलेंगे नियम, जानिए ग्राहकों पर क्या होगा असर

    15 अक्टूबर से ₹2,000 से ज्यादा UPI मर्चेंट पेमेंट पर MDR लागू होगा। पेट्रोल पंपों पर ₹5 शुल्क को लेकर डीलर्स के विरोध से ग्राहकों के भुगतान विकल्प बदल सकते हैं।

    मध्यप्रदेश: ₹2,000 से ज्यादा के पेट्रोल-डीजल भुगतान के लिए UPI इस्तेमाल करने वाले ग्राहकों को जल्द नया नियम देखने को मिल सकता है। 15 अक्टूबर 2026 से हाई-वैल्यू UPI मर्चेंट ट्रांजैक्शन पर नया Merchant Discount Rate (MDR) लागू होना है। पेट्रोल और डीजल जैसे fuel transactions के लिए ₹2,000 से ऊपर के भुगतान पर flat ₹5 MDR तय किया गया है। इसी शुल्क का विरोध करते हुए मध्य प्रदेश के पेट्रोल पंप डीलर्स ने 16 अक्टूबर से ₹2,000 से ज्यादा के UPI भुगतान स्वीकार नहीं करने का फैसला किया है।

    इस फैसले का मतलब यह नहीं है कि पेट्रोल पंपों पर UPI पूरी तरह बंद हो जाएगा। ₹2,000 तक के भुगतान पर UPI जारी रहेगा। विवाद सिर्फ ₹2,000 से ज्यादा के merchant payment पर लगने वाले MDR को लेकर है। सरकार की व्यवस्था के मुताबिक यह शुल्क ग्राहक से सीधे वसूलने के लिए नहीं है, बल्कि merchant-side payment processing cost है।

    क्या बदलेगा 15 अक्टूबर से?

    नए framework में सामान्य eligible UPI merchant transactions पर ₹2,000 से ऊपर 0.4 प्रतिशत MDR रखा गया है। वहीं fuel, railway, telecom और कुछ अन्य श्रेणियों के लिए ₹2,000 से ऊपर flat ₹5 MDR का प्रावधान है। सामान्य category में बहुत बड़े transactions के लिए ₹300 की अधिकतम सीमा भी रखी गई है।

    इसलिए पेट्रोल पंप के मामले में 0.4 प्रतिशत और ₹5 MDR के बीच अंतर समझना जरूरी है। उदाहरण के लिए ₹10,000 के सामान्य eligible merchant UPI payment पर 0.4 प्रतिशत के हिसाब से ₹40 MDR बन सकता है, जबकि fuel transaction के लिए ₹2,000 से ऊपर flat ₹5 का प्रावधान है।

    ग्राहक को ₹5 अलग से देना होगा?

    नहीं। MDR को ग्राहक पर सीधे UPI शुल्क के रूप में डालने की व्यवस्था नहीं की गई है। इसका असर merchant और payment ecosystem के बीच होने वाली processing cost पर है। हालांकि पेट्रोल पंप डीलर्स का कहना है कि उनके कम और निर्धारित मार्जिन में यह अतिरिक्त लागत उठाना मुश्किल होगा।

    मध्य प्रदेश में 4,700 पेट्रोल पंपों पर असर

    मध्य प्रदेश में यह फैसला करीब 4,700 पेट्रोल पंपों को प्रभावित कर सकता है। मध्य प्रदेश पेट्रोलियम डीलर्स एसोसिएशन के अध्यक्ष अजय सिंह के मुताबिक प्रत्येक पंप पर रोजाना औसतन करीब 100 ऐसे ग्राहक होते हैं जिनका fuel payment ₹2,000 से ज्यादा होता है। एसोसिएशन ने अनुमान लगाया है कि MDR और GST को मिलाकर एक पंप पर करीब ₹590 प्रतिदिन और लगभग ₹17,700 प्रति माह का अतिरिक्त खर्च बैठ सकता है।

    इस गणना के आधार पर 4,700 पंपों पर संभावित लागत करीब ₹8.3 करोड़ प्रति माह बैठती है। यह डीलर्स के अनुमान पर आधारित गणना है, सरकार की ओर से जारी कोई स्वतंत्र cost assessment नहीं।

    डीलर्स क्यों कर रहे हैं विरोध?

    पेट्रोल पंप कारोबार में fuel की बिक्री पर dealer margin सीमित और निर्धारित होता है। डीलर्स का तर्क है कि बड़े UPI भुगतान पर flat MDR उनकी कमाई को सीधे प्रभावित करेगा। अजय सिंह ने कहा है कि पंप का profit margin बहुत कम है और इस अतिरिक्त खर्च को ग्राहकों से वसूलना भी आसान नहीं है।

    मध्य प्रदेश में डीलर्स ने इस मुद्दे पर अपने State-Level Coordinator को पत्र भी भेजा है और सरकार से UPI को MDR से छूट देने की मांग की है। उनका कहना है कि petrol pumps को credit और debit card transactions में पहले से MDR संबंधी छूट मिली हुई है, इसलिए UPI के लिए भी इसी तरह की राहत दी जानी चाहिए।

    ग्राहकों के पास कौन-कौन से विकल्प रहेंगे?

    अगर मध्य प्रदेश के डीलर्स का फैसला बिना बदलाव लागू होता है, तो ₹2,000 से ज्यादा के fuel payment पर ग्राहक को UPI के बजाय उपलब्ध दूसरे payment mode का इस्तेमाल करना पड़ सकता है।

    ₹2,000 तक के fuel payment के लिए UPI उपलब्ध रहेगा। मध्य प्रदेश डीलर्स एसोसिएशन ने debit और credit card payment सुविधा जारी रखने की बात कही है। इसलिए इसे पूरे पेट्रोल पंप पर cash-only व्यवस्था के रूप में समझना सही नहीं होगा। अलग-अलग पंपों पर उपलब्ध payment options अलग हो सकते हैं।

    क्या ₹2,000 से ज्यादा का UPI भुगतान पूरे देश में बंद होगा?

    नहीं। नया MDR framework पूरे देश में लागू होने वाला payment-cost framework है, लेकिन ₹2,000 से ज्यादा का UPI स्वीकार करना या न करना merchant का अलग operational decision हो सकता है।

    फिलहाल fuel dealers के बीच इसका विरोध कई जगह दिखाई दे रहा है। मध्य प्रदेश में 4,700 पंपों का फैसला सामने आया है, जबकि महाराष्ट्र में भी fuel dealers ने UPI पर MDR से छूट की मांग की है। मुंबई के पेट्रोल पंप संचालकों ने भी 15 अक्टूबर से high-value UPI payments रोकने की चेतावनी दी है, अगर fuel retailers को MDR से छूट नहीं मिलती।

    महाराष्ट्र में भी बढ़ रहा विरोध

    महाराष्ट्र में fuel dealers का कहना है कि ₹5 का flat MDR कम margin वाले कारोबार पर अतिरिक्त दबाव डाल सकता है। महाराष्ट्र के dealer organisations इस मुद्दे पर 27 सितंबर के आसपास आगे की रणनीति पर फैसला लेने की बात कह चुके हैं।

    मुंबई में डीलर्स की मांग सिर्फ MDR हटाने तक सीमित नहीं है। उनका एक प्रस्ताव यह भी है कि अगर UPI payment पर कोई processing cost आती है तो उसका बोझ oil marketing companies उठाएं, ताकि पेट्रोल पंप डीलर्स के निर्धारित margin पर सीधा असर न पड़े।

    सरकार और डीलर्स के बीच बातचीत जारी

    इस विवाद के बीच 17 सितंबर को All India Petroleum Dealers Association (AIPDA) के प्रतिनिधियों ने Petroleum and Natural Gas Ministry के वरिष्ठ अधिकारियों से मुलाकात की। बैठक में UPI fuel transactions पर MDR exemption की मांग उठाई गई। मंत्रालय की ओर से MDR व्यवस्था के पीछे digital payment infrastructure को मजबूत करने का उद्देश्य भी समझाया गया।

    AIPDA के अध्यक्ष अजय बंसल ने भी Finance Minister के हस्तक्षेप की मांग करते हुए fuel retailers को ₹2,000 से ऊपर UPI payments पर MDR से पूरी छूट देने की मांग की है।

    CAIT ने भी जताई चिंता

    Confederation of All India Traders (CAIT) ने मध्य प्रदेश में high-value UPI payments रोकने के फैसले को डिजिटल transactions के लिए चिंता का विषय बताया है। CAIT के भोपाल जिला अध्यक्ष और मध्य प्रदेश मीडिया प्रभारी धर्मेंद्र शर्मा के अनुसार राज्य के करीब 4,700 पेट्रोल पंप इस फैसले से प्रभावित हो सकते हैं।

    धर्मेंद्र शर्मा ने यह भी स्पष्ट किया कि सामान्य merchant transactions और fuel transactions के MDR में अंतर है। सामान्य eligible merchant payment पर 0.4 प्रतिशत MDR लागू होता है, जबकि fuel transactions के लिए ₹2,000 से ऊपर flat ₹5 MDR का प्रावधान है।

    एक और जरूरी बात: UPI पूरी तरह महंगा नहीं हुआ है

    नए MDR framework का मतलब यह नहीं है कि हर UPI payment पर शुल्क लगेगा। ₹2,000 तक के merchant payments पर MDR नहीं लगाया गया है और person-to-person UPI transactions भी इस merchant MDR व्यवस्था से अलग हैं। सरकार के मुताबिक नए framework से अधिकांश छोटे-value P2M transactions प्रभावित नहीं होंगे।

    आगे क्या होगा?

    अब मुख्य सवाल यह है कि 15 अक्टूबर से पहले fuel dealers को MDR से छूट मिलती है या नहीं। सरकार और petroleum dealers के बीच बातचीत हो चुकी है, लेकिन उपलब्ध ताजा जानकारी में fuel sector के लिए पूर्ण MDR exemption की अंतिम घोषणा सामने नहीं आई है। इसलिए मध्य प्रदेश में 16 अक्टूबर से ₹2,000 से ऊपर UPI रोकने का फैसला फिलहाल डीलर्स की घोषित स्थिति है और इसमें सरकार के अगले फैसले के आधार पर बदलाव हो सकता है।

    ग्राहकों के लिए फिलहाल सबसे जरूरी बात यही है कि ₹2,000 तक का UPI payment जारी रहेगा, जबकि इससे ज्यादा के fuel payment के लिए 15-16 अक्टूबर के बाद संबंधित पेट्रोल पंप पर उपलब्ध payment option पहले से जांचना जरूरी होगा।

  • YouTube Monetization Secrets 2026 That Creators Ignore

    YouTube Monetization Secrets 2026 That Creators Ignore

    YouTube Monetization tips 2026 to grow earnings faster with AdSense, Shorts, AI tools, RPM strategies, SEO methods, and creator income hacks.

    YouTube monetization in 2026 is no longer limited to AdSense income alone. Creators are building full-time businesses through affiliate marketing, digital products, sponsorships, memberships, AI-assisted channels, and YouTube Shopping. At the same time, competition has increased. Because of that, creators who understand watch time, audience intent, RPM optimization, and YouTube SEO are earning significantly more than channels with larger subscriber counts.

    Many beginners still believe that YouTube success depends only on viral videos. However, data across creator-focused platforms like YouTube Creator Academy, TubeBuddy, vidIQ, and Thinkific shows a different reality. Channels that focus on monetizable audiences, longer session watch time, niche authority, and multiple income streams are outperforming entertainment-only channels.

    This complete guide explains how YouTube monetization works in 2026, how creators actually earn money, what RPM ranges are realistic, how Shorts compare to long-form videos, which niches pay the most, how AI tools are changing content production, and how beginners can realistically reach their first $100, $1,000, and beyond.

    Is YouTube Monetization Still Worth It in 2026?

    Yes. YouTube remains one of the strongest creator economy platforms because it combines search traffic, recommendation traffic, evergreen content, and multiple monetization systems in one ecosystem.

    Unlike short-lived viral platforms, YouTube videos can continue generating views and revenue for years. A single evergreen tutorial or finance video can produce passive income long after publication.

    read also- How to Increase Subscribers on YouTube

    The biggest advantage of YouTube monetization is income diversification. Creators now earn from:

    • AdSense revenue
    • Affiliate marketing
    • Brand sponsorships
    • YouTube Shopping
    • Channel memberships
    • Super Thanks
    • Digital product sales
    • Coaching and consulting
    • Online courses
    • BrandConnect collaborations

    This means even small channels can become profitable if their audience is targeted correctly.

    YouTube vs TikTok vs Instagram Earnings

    PlatformAverage RPMEvergreen PotentialSearch TrafficSponsorship Value
    YouTubeHighExcellentVery StrongVery High
    TikTokLowWeakLimitedMedium
    InstagramMediumModerateWeakHigh
    Facebook VideoMediumModerateModerateMedium

    YouTube remains stronger because videos continue ranking in search results for years. That gives creators recurring traffic and stable monetization opportunities.

    YouTube Partner Program Requirements 2026

    The YouTube Partner Program (YPP) is the gateway to monetization. Without YPP approval, creators cannot access full ad revenue systems.

    Standard Monetization Path

    To unlock full YouTube monetization, creators typically need:

    • 1,000 subscribers
    • 4,000 public watch hours in the last 12 months

    OR

    • 10 million eligible Shorts views in 90 days

    Once approved, creators can enable ads and other earning features.

    read also – Best Online Earning Websites in India That Really Pay

    Early Monetization Features

    Some regions now support earlier monetization access with reduced requirements:

    • 500 subscribers
    • 3 public uploads in 90 days
    • 3,000 watch hours OR 3 million Shorts views

    This unlocks:

    • Super Thanks
    • Memberships
    • Fan funding features

    However, full AdSense monetization still requires higher thresholds.

    YouTube Monetization Policies

    Creators must also follow:

    • Original content policies
    • Copyright rules
    • Community guidelines
    • Advertiser-friendly content standards

    Channels using reused content without meaningful transformation often face rejection.

    read also – Best Work From Home Jobs in India With High Income

    How Much Does YouTube Pay in 2026?

    This is the most important question for new creators. However, YouTube income varies heavily based on niche, audience country, watch time, and advertiser demand.

    Understanding CPM vs RPM

    • CPM = advertiser payment per 1,000 ad impressions
    • RPM = creator earnings after YouTube’s share

    RPM matters more because it reflects actual creator income.

    YouTube RPM by Niche

    NicheEstimated RPM
    Finance$12–$50
    Insurance$15–$45
    Investing$10–$40
    Business$8–$25
    Technology$4–$15
    Education$5–$18
    Digital Marketing$6–$20
    Health$3–$12
    Gaming$1–$5
    Entertainment$0.50–$3
    Memes$0.20–$2

    Finance and business channels usually attract high-paying advertisers. Entertainment channels often receive massive views but lower RPM.

    Country-Wise RPM Comparison

    CountryTypical RPM
    USA$5–$15
    Canada$4–$12
    UK$4–$12
    Australia$5–$14
    Germany$3–$10
    India$0.50–$2
    Pakistan$0.20–$1
    Bangladesh$0.15–$0.80

    Creators targeting US audiences often earn significantly more even with fewer views.

    Shorts vs Long-Form Revenue

    Content TypeAverage RPM
    Shorts$0.03–$0.07
    Long-Form Videos$1–$5+

    Shorts help channels grow rapidly. However, long-form content generates much stronger monetization.

    The best strategy is combining both:

    • Shorts for reach
    • Long-form for revenue

    Time-to-First-$100 Roadmap

    MilestoneEstimated Time
    First 100 Subscribers1–3 Months
    Monetization Approval3–12 Months
    First $1004–12 Months
    $1,000/Month12–24 Months

    Channels focused on searchable content often monetize faster than entertainment channels.

    10 Best Ways to Earn Through YouTube Monetization

    YouTube

    1. AdSense Revenue

    AdSense remains the foundation of YouTube monetization.

    To maximize ad revenue:

    • Create longer videos
    • Increase watch time
    • Add mid-roll ads strategically
    • Target high-value niches

    Videos over 8 minutes can include additional ads, increasing RPM significantly.

    2. YouTube Shorts Monetization

    Shorts can grow subscribers quickly. Viral Shorts often bring millions of views rapidly.

    However:

    • RPM is lower
    • Viewer loyalty is weaker
    • Conversion into long-form viewers is essential

    The best creators use Shorts as traffic funnels toward higher RPM videos.

    3. Affiliate Marketing

    Affiliate marketing is often more profitable than AdSense.

    Creators recommend:

    • Software tools
    • Courses
    • Hosting services
    • Gadgets
    • AI tools

    Affiliate links in descriptions generate commissions when viewers purchase products.

    Popular affiliate networks include:

    4. Brand Sponsorships

    Sponsors pay creators for audience access.

    Typical sponsorship rates:

    • Small creators: $50–$500
    • Mid-size channels: $500–$5,000
    • Large channels: $10,000+

    Brands value audience trust more than subscriber count alone.

    5. YouTube Shopping Affiliate Program

    YouTube Shopping has become a major earning feature in 2026.

    Creators can:

    • Tag products in videos
    • Earn affiliate commissions
    • Sell merchandise directly

    This is especially powerful for:

    • Tech channels
    • Beauty creators
    • Fitness influencers
    • Review channels

    6. Channel Memberships

    Memberships provide recurring monthly income.

    Popular membership perks include:

    • Exclusive livestreams
    • Members-only videos
    • Early access content
    • Community badges
    • Private Discord groups

    7. Super Thanks and Super Chat

    Live stream audiences often support creators directly.

    To increase fan contributions:

    • Engage viewers by name
    • Stream consistently
    • Use Q&A sessions
    • Create audience loyalty

    8. Selling Digital Products

    Creators increasingly sell:

    • E-books
    • Templates
    • Courses
    • Presets
    • Notion packs

    Digital products scale better than AdSense because profit margins are much higher.

    9. Coaching and Consulting

    Expert channels often convert viewers into clients.

    High-performing coaching niches include:

    • Fitness
    • Finance
    • SEO
    • AI tools
    • Business growth

    Even small channels can generate significant consulting revenue.

    10. Licensing and Content Syndication

    Viral clips can be licensed to:

    • News publishers
    • Media platforms
    • Brands

    Some creators earn substantial passive income from licensing alone.

    AI Tools Changing YouTube Monetization in 2026

    AI has transformed video production completely.

    Creators now produce faster, cheaper, and more optimized content.

    AI Script Writing Tools

    Popular options include:

    These tools help:

    • Generate scripts
    • Improve hooks
    • Create outlines
    • Research topics

    AI Thumbnail Creation Tools

    Thumbnail CTR directly affects monetization.

    Popular tools:

    AI Video Editing Tools

    Modern creators increasingly use:

    These tools reduce editing time dramatically.

    AI SEO Tools for YouTube

    SEO optimization tools include:

    They help with:

    • Keyword research
    • CTR analysis
    • Competitor tracking
    • Tag optimization

    Faceless YouTube Channels in 2026

    Faceless channels are growing rapidly because creators can earn without appearing on camera.

    Best Niches for Faceless Channels

    High-performing faceless categories:

    • Finance
    • Motivation
    • AI tutorials
    • Tech explainers
    • History
    • Luxury content
    • Documentary videos

    AI Voiceover Tools

    Popular voice generators:

    Stock Footage Sources

    Reliable platforms:

    YouTube SEO Strategies That Increase Earnings

    YouTube SEO affects both traffic and monetization.

    Higher visibility means:

    • More views
    • Better watch time
    • Higher RPM potential

    Keyword Research for YouTube

    Good keywords usually:

    • Solve problems
    • Have search demand
    • Match audience intent

    Use:

    • YouTube autocomplete
    • Google Trends
    • vidIQ
    • TubeBuddy

    Thumbnail Optimization

    Strong thumbnails:

    • Use emotional expressions
    • Highlight contrast
    • Include minimal text
    • Create curiosity

    CTR improvements often lead to massive growth.

    Watch Time Optimization

    To improve retention:

    • Use strong hooks
    • Remove unnecessary intros
    • Add pattern interrupts
    • Increase pacing

    Longer watch sessions improve algorithm performance.

    Advanced RPM Optimization Tips

    Higher RPM creators optimize audience quality rather than only chasing views.

    Target High-Value Audiences

    Advertisers pay more for:

    • US viewers
    • Business professionals
    • Buyers with purchasing intent

    Upload Longer Videos

    Longer content supports:

    • More ads
    • Better session watch time
    • Higher total revenue

    Strategic Mid-Roll Ads

    Mid-roll ads perform best when inserted naturally during topic transitions.

    Too many ads reduce retention.

    Tax Guide for YouTube Monetization

    Taxes are one of the least understood areas of creator income.

    W-8BEN Form for Non-US Creators

    International creators usually submit the W-8BEN form to reduce US tax withholding.

    Google Tax Withholding

    Creators earning from US audiences may see partial withholding taxes.

    Income Tax for Indian YouTubers

    Indian creators typically report:

    • AdSense income
    • Sponsorship revenue
    • Affiliate commissions

    Professional tax consultation is strongly recommended.

    Beginner Mistakes That Delay YouTube Monetization

    Uploading Random Content

    Channels without niche focus struggle to build audience loyalty.

    Ignoring Audience Retention

    Watch time matters more than views alone.

    Overusing Copyrighted Content

    Reused clips often trigger monetization rejection.

    Focusing Only on Subscribers

    RPM, retention, and audience quality matter more.

    Weak Thumbnails

    Poor thumbnails destroy click-through rate.

    Best YouTube Monetization Niches in 2026

    NicheMonetization Potential
    FinanceVery High
    AI ToolsVery High
    BusinessVery High
    Software TutorialsHigh
    EducationHigh
    ProductivityHigh
    HealthMedium-High
    GamingMedium
    EntertainmentMedium
    VlogsMedium-Low

    Frequently Asked Questions

    How many views are needed to earn money on YouTube?

    Views alone do not matter. Monetization depends on RPM, audience country, niche, and engagement.

    Can small channels earn money?

    Yes. Small targeted channels often outperform large untargeted channels.

    Which niche pays the highest RPM?

    Finance, insurance, and investing usually pay the highest RPM.

    Are Shorts good for monetization?

    Shorts help growth, but long-form videos generally produce higher income.

    How long does YouTube monetization take?

    Most creators take between 3 and 12 months to reach monetization requirements.

    Is faceless YouTube allowed?

    Yes. Faceless channels are fully allowed if they follow original content guidelines.

    Can AI-generated content be monetized?

    Yes, but content must provide value and avoid low-quality automation.

    Conclusion

    YouTube monetization in 2026 rewards creators who combine audience trust, SEO optimization, long-form content, AI-assisted workflows, and diversified income systems. AdSense alone is no longer enough. Successful creators now build complete creator businesses around their channels.

    The fastest-growing channels are focusing on:

    • High-RPM niches
    • Searchable evergreen content
    • Audience retention
    • Multiple revenue streams
    • AI-assisted production
    • Faceless scaling systems

    Creators who start today still have strong opportunities because YouTube continues prioritizing useful, watchable, and experience-driven content.

    The biggest advantage now belongs to creators who treat YouTube like a long-term business instead of chasing short-term viral trends.

    Disclaimer

    This article is for educational and informational purposes only. Earnings mentioned in this article are estimated averages and may vary depending on niche, audience location, engagement, advertiser demand, and YouTube policy updates. We do not guarantee specific income results.

    Some external links in this article may be do-follow or no-follow links depending on editorial preference, sponsorship status, or affiliate disclosure requirements.

    Always review the latest policies directly from YouTube and consult a certified tax professional before making financial or tax-related decisions.

  • Best Tax Saving Investment Options in India 2026 – ELSS, PPF, NPS & Tax Saving Guide

    Best Tax Saving Investment Options in India 2026 – ELSS, PPF, NPS & Tax Saving Guide

    Explore the best tax saving investment options in India 2026 including ELSS, PPF, NPS, tax saving FD, ULIP, and insurance plans to reduce income tax legally while building long-term wealth.

    Tax Saving Investment Options in India 2026 – Best Ways to Save Income Tax Legally

    Tax planning has become one of the most important financial activities for Indian families in 2026. Rising income levels, changing tax regulations, inflation, and long-term financial responsibilities are encouraging people to look for the best tax saving investment options that not only reduce tax liability but also help build future wealth.

    Whether you are a salaried employee, freelancer, entrepreneur, business owner, or retiree, smart tax planning can help you legally save thousands or even lakhs of rupees every year. Many people make the mistake of investing only at the end of the financial year without understanding the long-term benefits of proper tax-saving strategies.

    India offers several tax-saving investment opportunities under different sections of the Income Tax Act, including Section 80C, Section 80CCD, and Section 80D. Investors can choose from equity-linked investments, government-backed schemes, retirement plans, insurance products, and fixed-income instruments according to their financial goals and risk appetite.

    This detailed guide explains the best tax saving investment options in India in 2026, their returns, risks, lock-in periods, tax deductions, advantages, disadvantages, and ideal strategies for long-term financial growth.

    Why Tax Saving Investments Are Important

    Most people focus only on earning money, but wealth creation also depends heavily on tax management. Efficient tax planning helps investors keep more of their income while building a financially secure future.

    Major Benefits of Tax Saving Investments

    Best tax saving investment options in India 2026 including ELSS PPF NPS and tax saving calculator

    Reduce Taxable Income

    Eligible investments help reduce total taxable income legally.

    Build Long-Term Wealth

    Investments like ELSS, NPS, and PPF help create wealth through compounding.

    Improve Retirement Planning

    Retirement-focused investments provide financial security after retirement.

    Financial Discipline

    Regular investments encourage disciplined saving habits.

    Protection Against Emergencies

    Insurance-linked tax-saving products provide financial safety for families.

    Understanding Section 80C Tax Benefits

    Section 80C is one of the most important tax-saving provisions available to Indian taxpayers.

    Maximum Deduction Limit

    Taxpayers can claim deductions up to:

    ₹1.5 lakh annually

    Eligible Investment Options

    • ELSS Mutual Funds
    • Public Provident Fund (PPF)
    • National Savings Certificate (NSC)
    • Tax Saving Fixed Deposits
    • Life Insurance Premiums
    • Sukanya Samriddhi Yojana
    • Employee Provident Fund (EPF)

    Using Section 80C strategically can significantly reduce annual tax burden.

    Tax Saving Investment Calculator

    Calculator Meaning:

    Annual Income = Your yearly taxable income
    Tax Saving Investment = Amount invested under Section 80C
    Estimated Tax Saved = Approximate tax reduction
    Estimated Tax Saved
    ₹0

    Best Tax Saving Investment Options in India 2026

    1. ELSS Mutual Funds

    Equity Linked Savings Schemes (ELSS) are among the most popular tax saving investment options in India.

    ELSS funds primarily invest in equities and provide Section 80C tax benefits along with wealth creation opportunities.

    Key Benefits of ELSS

    • Tax deduction up to ₹1.5 lakh
    • Potentially high returns
    • Shortest lock-in period of 3 years
    • Professional fund management
    • SIP investment option available

    Risks of ELSS

    Since ELSS funds are market-linked investments, returns are not guaranteed and can fluctuate based on stock market conditions.

    Ideal For

    • Young investors
    • Long-term wealth creators
    • Investors comfortable with market risks

    2. Public Provident Fund (PPF)

    PPF remains one of the safest and most trusted long-term tax-saving investments in India.

    It is backed by the Government of India and provides tax-free maturity benefits.

    Advantages of PPF

    • Guaranteed government-backed returns
    • Tax-free maturity amount
    • Long-term compounding benefits
    • Safe investment option

    Lock-in Period

    15 Years

    Best For

    • Conservative investors
    • Long-term retirement planning
    • Risk-averse families

    3. National Pension System (NPS)

    NPS has become highly popular among salaried employees and retirement planners due to additional tax benefits and long-term wealth creation potential.

    Tax Benefits

    Section 80C

    Up to ₹1.5 lakh deduction

    Additional Section 80CCD(1B)

    Additional ₹50,000 deduction

    Major Advantages

    • Retirement corpus creation
    • Low-cost investment structure
    • Equity and debt exposure
    • Long-term disciplined investing

    Best For

    • Salaried employees
    • Retirement-focused investors
    • Long-term planners

    4. Tax Saving Fixed Deposits (FDs)

    Tax-saving fixed deposits are ideal for investors seeking stability and predictable returns.

    Features

    • Fixed interest returns
    • 5-year lock-in period
    • Section 80C eligibility
    • Low investment risk

    Advantages

    • Safe investment
    • Stable income
    • Suitable for conservative investors

    Disadvantages

    • Lower returns compared to equities
    • Interest income may be taxable

    5. Life Insurance Plans

    Life insurance plays an important role in both financial protection and tax saving.

    Popular Insurance Options

    • Term Insurance
    • ULIPs
    • Endowment Plans

    Tax Benefits

    • Premium deduction under Section 80C
    • Tax-free maturity under Section 10(10D)

    Why Insurance Matters

    Insurance protects family members financially during emergencies and unexpected situations.

    6. Sukanya Samriddhi Yojana (SSY)

    SSY is one of the best government-backed savings schemes for parents with daughters.

    Key Benefits

    • Attractive interest rates
    • Tax-free maturity
    • Long-term savings discipline
    • Government-backed security

    Best For

    • Parents planning future education or marriage expenses for daughters

    7. Senior Citizens Savings Scheme (SCSS)

    SCSS is designed specifically for senior citizens looking for stable returns and income security.

    Features

    • Government-backed scheme
    • Regular income generation
    • Safe investment
    • Section 80C tax benefits

    Suitable For

    • Retired individuals
    • Senior citizens seeking low-risk investments

    8. Unit Linked Insurance Plans (ULIPs)

    ULIPs combine insurance and market-linked investments.

    Benefits

    • Investment + insurance combination
    • Long-term wealth creation
    • Tax-saving benefits

    Risks

    Returns depend on market performance.

    Safe vs High Return Tax Saving Investments

    Investment TypeRisk LevelReturn Potential
    PPFLowModerate
    Tax Saving FDLowModerate
    ELSSHighHigh
    ULIPMediumModerate to High
    NPSMediumModerate

    Choosing the right balance between safety and growth is important for long-term financial success.

    Tax Saving Strategies for Salaried Employees

    Salaried employees can maximize tax savings through proper diversification.

    Recommended Investment Mix

    • ELSS Funds
    • PPF
    • NPS
    • Health Insurance
    • Term Insurance

    Using multiple investment options improves both tax efficiency and portfolio stability.

    Tax Saving Strategies for Business Owners

    Business owners often prefer flexible and growth-oriented investments.

    Recommended Options

    • ELSS Funds
    • ULIPs
    • NPS
    • Insurance Plans
    • Retirement Investments

    Strategic tax planning helps business owners reduce overall tax burden.

    Importance of Compounding in Tax Saving Investments

    Long-term investments benefit significantly from compounding growth.

    A = P(1 + r n )nt
    A = Final Amount
    P = Principal
    r = Interest Rate
    n = Compound Frequency
    t = Time (Years)
    ₹100000
    12%
    12
    10 Years
    Final Compound Value
    ₹0

    The earlier investors start investing, the larger their wealth can grow over time.

    Common Tax Saving Investment Mistakes

    Investing at the Last Minute

    Last-minute decisions often result in poor investment choices.

    Ignoring Risk Profile

    Investors should choose investments based on personal risk tolerance.

    Focusing Only on Tax Saving

    Investments should support long-term financial goals, not just tax reduction.

    Ignoring Lock-in Periods

    Always understand withdrawal restrictions before investing.

    Best Tax Saving Investment Strategy in 2026

    A balanced strategy may include:

    • 40% Equity investments
    • 30% Safe debt instruments
    • 20% Retirement investments
    • 10% Insurance coverage

    Diversification helps reduce risks while improving long-term growth potential.

    Tax Planning Tips for 2026

    1. Start tax planning early
    2. Maximize Section 80C benefits
    3. Diversify investments
    4. Invest according to goals
    5. Review investments annually
    6. Avoid emotional investing
    7. Maintain emergency savings

    Frequently Asked Questions

    Which is the best tax saving investment option in India?

    ELSS, PPF, and NPS are among the best tax saving investment options depending on risk tolerance and financial goals.

    Is ELSS better than PPF?

    ELSS offers higher return potential but carries market risk. PPF provides stable and guaranteed returns.

    Can tax-saving investments create wealth?

    Yes. Investments like ELSS, NPS, and PPF help generate long-term wealth through compounding.

    What is the safest tax saving investment?

    PPF and tax-saving fixed deposits are considered among the safest investment options.

    Is NPS good for retirement planning?

    Yes. NPS is one of the best retirement-focused tax-saving investments available in India.

    Are tax-saving FDs risk-free?

    Tax-saving FDs are relatively safe because they are backed by banks, though returns may be lower than equities.

    How much tax can I save under Section 80C?

    You can claim deductions up to ₹1.5 lakh annually under Section 80C.

    Final Thoughts

    Choosing the best tax saving investment options in India in 2026 requires balancing tax efficiency, financial goals, risk tolerance, and long-term wealth creation. Investors should avoid investing blindly only for tax benefits and instead focus on building a strong financial future.

    A diversified portfolio combining ELSS, PPF, NPS, insurance, and safe fixed-income investments can help reduce taxes while creating sustainable long-term wealth.

    Smart tax planning is not just about saving money today — it is about achieving financial freedom in the future.

  • Financial Planning Guide for Indian Families 2026 – Smart Saving, Investment & Retirement Tips

    Financial Planning Guide for Indian Families 2026 – Smart Saving, Investment & Retirement Tips

    Read the complete financial planning guide for Indian families in 2026 including budgeting, savings, insurance, SIPs, retirement planning, tax saving, and smart investment tips for long-term financial security.

    Financial Planning Guide for Indian Families 2026

    Financial planning has become one of the most important responsibilities for Indian families in 2026. Rising inflation, healthcare costs, education expenses, and uncertain economic conditions are forcing families to manage money more carefully than ever before. A strong financial planning guide helps families organize income, savings, investments, insurance, and retirement goals in a structured way.

    Many Indian households struggle financially not because they earn less, but because they lack proper money management strategies. Smart financial planning helps families reduce debt, prepare for emergencies, grow wealth, and secure a stable future.

    Whether you are a salaried employee, business owner, freelancer, or retired individual, financial planning is essential for long-term success. Proper planning ensures that your family can handle unexpected situations without financial stress.

    This complete financial planning guide explains budgeting, savings, investment strategies, retirement planning, insurance, tax-saving options, and common financial mistakes Indian families should avoid in 2026.

    read also – Best Tax Saving Investment Options in India 2026 Guide

    Why Financial Planning Is Important in 2026

    Financial planning is not only about saving money. It is about creating financial security and achieving life goals systematically. Indian families today face several financial challenges, including:

    • Rising school and college fees
    • Increasing medical expenses
    • Inflation affecting daily living costs
    • Home loan and personal loan burdens
    • Retirement insecurity

    Without proper planning, families may struggle during emergencies or future financial needs.

    Major Benefits of Financial Planning

    Financial Planning Guide for Indian Families

    1. Emergency Fund Creation

    Unexpected situations such as job loss, medical emergencies, or business losses can affect financial stability. Emergency savings provide protection during difficult times.

    2. Better Expense Management

    Financial planning helps track spending habits and reduces unnecessary expenses.

    3. Wealth Creation

    Investments like SIPs, mutual funds, equities, and retirement plans help grow wealth over time.

    4. Child Education Planning

    Education costs in India continue to rise every year. Planning early helps parents avoid financial pressure later.

    5. Retirement Security

    Retirement planning ensures stable income after retirement years.

    6. Tax Saving Benefits

    Several investment options provide tax deductions under Indian tax laws.

    Step-by-Step Financial Planning Guide

    Step 1: Create a Monthly Budget

    Budgeting is the foundation of financial planning. Families should track monthly income and expenses carefully.

    Important Budget Categories

    • House rent or home loan EMI
    • Grocery expenses
    • Utility bills
    • School fees
    • Medical expenses
    • Transportation costs
    • Entertainment expenses
    • Savings and investments

    A proper budget helps identify unnecessary spending and improves savings discipline.

    50-30-20 Rule

    Many financial experts recommend:

    • 50% for essential expenses
    • 30% for lifestyle expenses
    • 20% for savings and investments

    This strategy improves financial balance.

    Step 2: Build an Emergency Fund

    Emergency savings are extremely important in uncertain economic conditions.

    How Much Emergency Fund Is Required?

    Financial experts suggest maintaining at least:

    • 6 months of expenses for salaried individuals
    • 12 months of expenses for business owners or freelancers

    Emergency funds should remain easily accessible in:

    • Savings accounts
    • Liquid mutual funds
    • Fixed deposits

    Avoid using emergency savings for vacations or luxury purchases.

    Step 3: Buy Health Insurance

    Healthcare expenses in India are increasing rapidly. A single hospitalization can destroy family savings.

    Why Health Insurance Is Important

    Health insurance helps cover:

    • Hospital bills
    • Surgeries
    • Medical treatments
    • Critical illness expenses

    Families should choose policies with:

    • Cashless hospitalization
    • High claim settlement ratio
    • Family floater coverage
    • Critical illness add-ons

    Health insurance is no longer optional in 2026.

    Step 4: Buy Life Insurance

    Life insurance protects family members financially if the earning member passes away unexpectedly.

    Best Life Insurance Option

    Term insurance is considered the most affordable and effective option.

    Benefits of Term Insurance

    • Low premium
    • High coverage
    • Financial protection for dependents
    • Tax benefits

    Experts recommend insurance coverage equal to at least 10–15 times annual income.

    Step 5: Start Investing Early

    One of the biggest financial mistakes people make is delaying investments.

    Starting investments early helps generate higher returns due to compounding.

    Understanding Compounding

    Compounding means earning returns on both the original investment and previous returns.

    The earlier you invest, the larger your wealth becomes over time.

    Compound Interest Formula

    A = P(1 + r n )nt
    Formula Meaning:

    A = Final Amount after interest
    P = Principal Amount (Initial Investment)
    r = Annual Interest Rate (%)
    n = Number of times interest compounds per year
    t = Total Time in Years
    Final Amount
    ₹0

    Even small monthly investments can create significant wealth over long periods.

    Best Investment Options for Indian Families in 2026

    1. Mutual Funds

    Mutual funds are among the most popular investment options in India.

    Advantages

    • Professional fund management
    • Diversification
    • SIP investment option
    • Long-term wealth creation

    Best For

    • Beginners
    • Salaried individuals
    • Long-term investors

    2. SIP (Systematic Investment Plan)

    SIPs allow investors to invest fixed amounts monthly.

    Benefits of SIPs

    • Disciplined investing
    • Rupee cost averaging
    • Affordable investment method
    • Long-term growth

    SIPs are ideal for middle-class families.

    3. Public Provident Fund (PPF)

    PPF remains one of the safest long-term investment options.

    Benefits

    • Government-backed security
    • Tax-free returns
    • Long-term savings discipline

    PPF is suitable for conservative investors.

    4. Fixed Deposits (FD)

    Fixed deposits provide stable returns with low risk.

    Suitable For

    • Senior citizens
    • Risk-averse investors
    • Short-term savings

    However, FD returns may struggle to beat inflation in the long run.

    5. Equity Investments

    Stock market investments can provide higher long-term returns.

    Important Tips

    • Invest for long term
    • Diversify portfolio
    • Avoid emotional trading
    • Research companies carefully

    Equity investments carry risks but offer strong wealth-building potential.

    Retirement Planning Guide

    Retirement planning should begin as early as possible.

    Many Indians depend heavily on children after retirement, but modern financial planning encourages self-dependence.

    Why Retirement Planning Matters

    • Rising healthcare costs
    • Longer life expectancy
    • Inflation impact
    • Financial independence

    Best Retirement Investment Options

    • National Pension System (NPS)
    • EPF
    • PPF
    • Mutual Funds
    • Retirement-focused SIPs

    Tax Saving Strategies in India

    Tax planning is an important part of financial management.

    Popular Tax-Saving Investments

    Section 80C Options

    • PPF
    • ELSS Mutual Funds
    • EPF
    • Life insurance premiums
    • Sukanya Samriddhi Yojana

    Health Insurance Tax Benefits

    Health insurance premiums qualify under Section 80D.

    Smart tax planning helps families save money legally.

    Financial Planning for Children’s Education

    Education costs in India are increasing rapidly every year.

    Parents should start investing early for:

    • School education
    • College fees
    • Professional courses
    • Foreign education

    Best Education Planning Options

    • Child mutual funds
    • SIPs
    • Sukanya Samriddhi Yojana
    • PPF

    Long-term investing reduces future financial pressure.

    Debt Management Tips

    Loans and EMIs can become a major financial burden if not managed carefully.

    Smart Debt Management Tips

    • Avoid unnecessary personal loans
    • Pay credit card bills on time
    • Maintain healthy credit score
    • Avoid multiple loans simultaneously

    High-interest debt should be cleared first.

    Common Financial Mistakes Indian Families Make

    1. Overspending

    Lifestyle inflation often destroys savings potential.

    2. Delaying Investments

    Waiting too long reduces wealth creation opportunities.

    3. No Emergency Fund

    Many families struggle during emergencies because they lack savings.

    4. Ignoring Insurance

    Without insurance, medical emergencies can become financially devastating.

    5. Depending Only on Fixed Deposits

    Inflation reduces real returns from traditional savings methods.

    Digital Financial Planning Trends in 2026

    Technology is transforming financial planning in India.

    Latest Trends

    • AI-based investment apps
    • Digital banking
    • Robo-advisors
    • Online SIP platforms
    • Instant insurance purchase
    • UPI-based investment systems

    Digital finance tools make money management easier and more accessible.

    Tips for Successful Financial Planning

    Track Expenses Regularly

    Monitor where money is being spent every month.

    Increase Savings Gradually

    Increase investments whenever income grows.

    Diversify Investments

    Avoid putting all money into one investment option.

    Review Financial Goals Annually

    Update plans according to income and life changes.

    Avoid Emotional Spending

    Focus on long-term financial security.

    Financial Planning for Middle-Class Families

    Middle-class Indian families often face the challenge of balancing savings, education costs, healthcare expenses, and lifestyle needs.

    Recommended Strategy

    • Maintain strict monthly budget
    • Build emergency savings first
    • Buy adequate insurance
    • Start SIP investments early
    • Avoid unnecessary loans

    Even small disciplined investments can create significant wealth over time.

    Financial Planning for Senior Citizens

    Senior citizens should focus on:

    • Stable income generation
    • Low-risk investments
    • Medical insurance
    • Capital protection

    Suitable Investment Options

    • Senior Citizen Savings Scheme
    • Fixed Deposits
    • Post Office Schemes
    • Monthly income plans

    Safety becomes more important than aggressive growth.

    Future of Financial Planning in India

    India’s financial sector is evolving rapidly due to digital banking and fintech innovation.

    Future trends include:

    • AI-driven financial advice
    • Personalized investment strategies
    • Faster digital loans
    • Automated budgeting tools
    • Paperless financial services

    Financial literacy is also improving among young Indians.

    Frequently Asked Questions

    What is financial planning?

    Financial planning is the process of managing income, savings, investments, insurance, and expenses to achieve long-term financial goals.

    Why is financial planning important for families?

    Financial planning helps families manage expenses, build savings, reduce debt, and secure their future financially.

    How much emergency fund should a family maintain?

    Experts recommend maintaining at least 6–12 months of living expenses as emergency savings.

    Which investment is best for beginners?

    SIPs and mutual funds are considered beginner-friendly investment options for long-term wealth creation.

    Is health insurance necessary in 2026?

    Yes. Rising healthcare costs make health insurance essential for financial protection.

    When should retirement planning begin?

    Retirement planning should start as early as possible to maximize compounding benefits.

    What are the safest investment options in India?

    PPF, fixed deposits, and government-backed schemes are among the safest investment options.

    How can Indian families reduce financial stress?

    Proper budgeting, disciplined savings, insurance coverage, and long-term investing help reduce financial stress.

    Final Thoughts

    A strong financial planning guide helps Indian families achieve financial stability, reduce debt burdens, and build long-term wealth. In 2026, smart money management is more important than ever due to rising inflation and increasing living costs.

    Families that start budgeting, saving, investing, and protecting themselves with insurance early are more likely to enjoy financial freedom and peace of mind in the future.

    Financial planning is not only about money — it is about creating a secure and stress-free future for your entire family.

  • सीनियर सिटीजन को 30% टैक्स छूट का मैसेज फर्जी: BMC ने किया अलर्ट

    सीनियर सिटीजन को 30% टैक्स छूट का मैसेज फर्जी: BMC ने किया अलर्ट

    सोशल मीडिया पर वायरल हो रहे “ज्येष्ठ नागरिकों को 30% प्रॉपर्टी टैक्स छूट” वाले संदेश को BMC ने फर्जी बताया। निगम ने अपील की—नागरिक वॉर्ड ऑफिस न पहुंचें।

    मुंबई: सोशल मीडिया पर तेजी से वायरल हो रहे उस संदेश को BMC ने पूरी तरह फर्जी करार दिया है, जिसमें दावा किया गया था कि महाराष्ट्र सरकार के हाउसिंग पॉलिसी 2025 के तहत वरिष्ठ नागरिकों को उनकी रेजिडेंशियल प्रॉपर्टी पर 30% टैक्स छूट दी जा रही है। BMC ने साफ कहा है कि नगर निगम अधिनियम 1888 में ऐसी कोई भी प्रावधान नहीं है और वरिष्ठ नागरिक अनावश्यक रूप से वॉर्ड ऑफिसों में भीड़ न लगाएँ।

    सोशल मीडिया पर वायरल मैसेज से बढ़ी वॉर्ड ऑफिसों में भीड़

    पिछले कुछ दिनों से WhatsApp, Facebook और दूसरे सोशल मीडिया प्लेटफॉर्म पर एक संदेश बड़े पैमाने पर वायरल हो रहा था।
    उसमें लिखा था कि “ज्येष्ठ नागरिक को उनकी रेजिडेंशियल प्रॉपर्टी पर 30% प्रॉपर्टी टैक्स छूट मिलेगी”।

    इस संदेश को सच मानकर कई वरिष्ठ नागरिक मुंबई के अलग–अलग BMC वॉर्ड ऑफिसों में जानकारी के लिए पहुंच रहे थे।
    प्रशासन को अचानक बढ़ी भीड़ से दिक्कतें भी हुईं।

    BMC ने दिया स्पष्ट बयान: यह मैसेज 100% फर्जी

    बीएमसी ने प्रेस नोट जारी कर कहा—

    • नगर निगम अधिनियम 1888 में वरिष्ठ नागरिकों के लिए 30% टैक्स छूट का कोई नियम नहीं है।
    • नागरिक ऐसे मैसेज पर विश्वास न करें।
    • किसी भी प्रकार की पूछताछ के लिए वॉर्ड ऑफिस न आएँ, ताकि उन्हें बेवजह परेशानी न झेलनी पड़े।

    प्रशासन ने इसे सोशल मीडिया अफवाह करार दिया है।

    कौन-सी छूट वास्तव में लागू है? BMC ने बताया

    BMC ने सही जानकारी साझा करते हुए कहा—

    ✔ 1. 500 sq ft से कम रेजिडेंशियल प्रॉपर्टी पर टैक्स छूट

    1 जनवरी 2022 से मुंबई में 500 वर्ग फुट या उससे कम क्षेत्र वाली रेजिडेंशियल प्रॉपर्टीज को टैक्स में छूट दी गई है।

    ✔ 2. माजी सैनिक और शहीद परिवार को भी छूट

    • पूर्व सैनिक
    • उनकी विधवा
    • शहीद सैनिकों के अविवाहित परिवारजन
      इनकी एक प्रॉपर्टी को टैक्स में छूट मिलती है (शासन के टैक्स को छोड़कर)।

    ✔ वरिष्ठ नागरिकों के लिए कोई अलग से छूट नहीं

    बीएमसी ने दोहराया कि ज्येष्ठ नागरिकों के लिए 30% टैक्स छूट का संदेश पूरी तरह गलत है।


    FAQ सेक्शन

    1. क्या मुंबई में वरिष्ठ नागरिकों को प्रॉपर्टी टैक्स में 30% छूट मिलती है?

    नहीं, बीएमसी ने साफ कहा है कि ऐसा कोई नियम मौजूद नहीं है। वायरल मैसेज पूरी तरह फर्जी है।

    2. क्या इस फर्जी मैसेज के कारण बीएमसी कार्यालयों में भीड़ बढ़ी?

    हाँ, कई वरिष्ठ नागरिक वॉर्ड ऑफिस पहुंच गए थे, इसलिए बीएमसी ने स्पष्टीकरण जारी किया।

    3. वास्तव में मुंबई में किसे टैक्स छूट मिलती है?

    500 sq ft से कम क्षेत्र वाली रिहायशी प्रॉपर्टी को और पूर्व सैनिक/शहीद परिवार को छूट मिलती है।

    4. वरिष्ठ नागरिकों को कोई विशेष टैक्स छूट है?

    नहीं, वरिष्ठ नागरिकों के लिए अलग से कोई छूट लागू नहीं है।

    5. सही जानकारी कहाँ से लें?

    बीएमसी की आधिकारिक वेबसाइट, प्रेस नोट या वॉर्ड ऑफिस में अधिकृत अधिकारियों से।

  • भारत में सोने का नया युग: रिकॉर्ड दामों ने बदल दी खरीददारी की परंपरा, अब झुकाव निवेश की ओर

    भारत में सोने का नया युग: रिकॉर्ड दामों ने बदल दी खरीददारी की परंपरा, अब झुकाव निवेश की ओर

    भारत में सोने की कीमतें इतिहास के सबसे ऊंचे स्तर पर पहुंच गई हैं — ₹1.30 लाख प्रति 10 ग्राम। इस तेजी ने दीवाली और धनतेरस पर पारंपरिक ज्वेलरी खरीदने के चलन को बदल दिया है। अब लोग भारी गहनों की जगह गोल्ड कॉइन, बार और डिजिटल गोल्ड में निवेश कर रहे हैं।

    मुंबई: 21 अक्टूबर 2025 — भारत में सोने की कीमतों ने इस साल अब तक का सबसे ऊंचा स्तर छू लिया है। 24 कैरेट गोल्ड का रेट लगभग ₹1,30,860 प्रति 10 ग्राम पहुंच गया है — यानी साल की शुरुआत से अब तक करीब 66% की बढ़ोतरी।

    इस भारी उछाल ने न सिर्फ लोगों की जेब पर असर डाला है, बल्कि दीवाली और धनतेरस जैसे त्योहारों की परंपरा को भी पूरी तरह बदल दिया है। अब लोग सोने के भारी गहने कम और गोल्ड कॉइन व बार में निवेश ज्यादा कर रहे हैं।

    अब गहनों से ज्यादा निवेश पर फोकस

    पहले धनतेरस पर सोने के हार, कंगन और झुमके बिकते थे, अब लोग उसी पैसे से 10 या 20 ग्राम के गोल्ड कॉइन ले रहे हैं। सोने के रेट 18 अक्टूबर को ₹1,34,800 प्रति 10 ग्राम तक पहुंच गए — पिछले साल के मुकाबले 60% से ज्यादा महंगा। हालांकि सोने की बिक्री का वॉल्यूम 10-15% घटा है, लेकिन कुल कारोबार का मूल्य बढ़ा क्योंकि कीमतें रिकॉर्ड ऊंचाई पर हैं।

    क्यों बढ़ रही हैं सोने की कीमतें?

    • वैश्विक तनाव और कमज़ोर अमेरिकी डॉलर
    • सेंट्रल बैंकों की गोल्ड खरीदारी में तेजी
    • ब्याज दरों में कटौती की उम्मीदें
    • निवेशकों का भरोसा — सोना सुरक्षित विकल्प

    2025 की शुरुआत से ही अंतरराष्ट्रीय मार्केट में सोने की कीमतें $4,000 प्रति औंस के पार चली गई हैं, और भारत में उसी का सीधा असर देखा जा रहा है।

    ज्वेलरी कंपनियों पर असर — कौन फायदे में, कौन घाटे में

    फायदे में रहने वाले ब्रांड्स:

    • Titan Company (Tanishq, CaratLane) – हल्के डिज़ाइन, 9 कैरेट कलेक्शन और इन्वेस्टमेंट गोल्ड कॉइन से मार्केट में टॉप पर।
    • Kalyan Jewellers – शादी सीज़न और फ्रेंचाइज़ मॉडल की वजह से राजस्व बढ़ा।
    • MMTC-PAMP – निवेशक गोल्ड कॉइन और बार की खरीद में बढ़ोतरी से रिकॉर्ड मुनाफा।

    मिश्रित असर वाले ब्रांड्स:

    • Rajesh Exports – रिफाइनिंग में फायदा, लेकिन पारंपरिक ज्वेलरी की बिक्री में गिरावट।
    • PC Jeweller – सोने के दामों से वॉल्यूम घटा, अब डायमंड और सिल्वर पर फोकस।

    नुकसान में:

    • छोटे लोकल ज्वेलर्स – महंगे सोने और घटते ग्राहक आधार से जूझ रहे हैं।
      अब उपभोक्ता भरोसेमंद ब्रांड्स या डिजिटल प्लेटफॉर्म की ओर जा रहे हैं।

    सोने में निवेश बढ़ा, लोन मार्केट भी गर्म

    • गोल्ड लोन कंपनियां जैसे मुथूट और मनप्पुरम को भारी फायदा —
      सोने की कीमत बढ़ने से लोन की वैल्यू भी बढ़ी।
    • ETF और डिजिटल गोल्ड प्लेटफॉर्म पर रिकॉर्ड इनफ्लो।
    • सरकारी बॉन्ड (SGB) की मांग भी तेजी से बढ़ रही है।

    सोने की बढ़त का असर भारत की अर्थव्यवस्था पर

    • भारत के पास लगभग 34,600 टन सोना है — कीमत करीब $3.8 ट्रिलियन।
    • कीमतें बढ़ने से घरों की कुल संपत्ति में इज़ाफा।
    • लेकिन सोने का इंपोर्ट बढ़ने से ट्रेड डेफिसिट भी बढ़ा —
      सितंबर 2025 में भारत का ट्रेड घाटा $32.15 बिलियन पहुंच गया।

    सरकार पर अब दबाव है कि इंपोर्ट ड्यूटी कम करे ताकि तस्करी पर लगाम लगे और रुपया संभले।

    लंबे समय में क्या हो सकता है?

    • 2026 तक सोना ₹1.40–₹1.60 लाख प्रति 10 ग्राम तक पहुंच सकता है।
    • सोने का फाइनेंशियलाइजेशन (ETFs, SGBs, डिजिटल गोल्ड) और तेज़ होगा।
    • सिल्वर और डायमंड मार्केट में भी मांग बढ़ेगी — सस्ते विकल्प के रूप में।
    • डिजिटल ज्वेलरी प्लेटफॉर्म नए निवेशकों के लिए आकर्षण का केंद्र बनेंगे।

    FAQ

    Q1. 2025 में भारत में सोने का रेट कितना है?
    24 कैरेट सोना लगभग ₹1,30,860 प्रति 10 ग्राम (अक्टूबर 2025 तक)।

    Q2. लोग अब गहनों की बजाय क्या खरीद रहे हैं?
    अब गोल्ड कॉइन, बार और डिजिटल गोल्ड में निवेश का ट्रेंड बढ़ा है।

    Q3. क्या सोने की कीमत और बढ़ेगी?
    एक्सपर्ट्स का मानना है कि 2026 तक सोना ₹1.40–₹1.60 लाख प्रति 10 ग्राम तक जा सकता है।

    Q4. किन कंपनियों को सोने की इस तेजी से फायदा हुआ है?
    Titan, Kalyan Jewellers और MMTC-PAMP जैसी कंपनियों को सीधा फायदा मिला है।

    Q5. क्या इससे अर्थव्यवस्था पर असर पड़ा है?
    हां, सोने के आयात से भारत का व्यापार घाटा बढ़ गया है और रुपया दबाव में है।

  • GST रेट कटौती: रोज़मर्रा के सामान से गाड़ियां तक सस्ती

    GST रेट कटौती: रोज़मर्रा के सामान से गाड़ियां तक सस्ती

    GST Council ने टैक्स ढांचा बदलकर चार स्लैब को घटाकर दो कर दिया। अब रोज़मर्रा के सामान, खाने-पीने की चीजें, इंश्योरेंस, गाड़ियां, सीमेंट और दवाइयां होंगी सस्ती। नया नियम 22 सितंबर से लागू होगा।

    डिजिटल डेस्क
    मुंबई: देश की सबसे बड़ी टैक्स सुधार बैठक में GST Council ने ऐतिहासिक निर्णय लिया है। अब तक चार स्लैब (5%, 12%, 18% और 28%) थे, जिन्हें घटाकर केवल दो स्लैब – 5% और 18% कर दिया गया है। इसके अलावा कुछ लग्ज़री और सिगरेट-तंबाकू जैसे उत्पादों पर 40% टैक्स लगाया जाएगा। GST rate cut: Everything from everyday items to vehicles becomes cheaper

    🥘 रोज़मर्रा की खाने-पीने की चीजें होंगी सस्ती

    • पनीर, सभी प्रकार की भारतीय रोटियां और पराठे अब बिल्कुल टैक्स फ्री (0%) होंगे।
    • मक्खन, घी, कॉर्न फ्लेक्स, नमकीन, पास्ता, इंस्टेंट नूडल्स, कॉफ़ी, जूस, आइसक्रीम, बिस्किट जैसी चीज़ों पर अब 5% GST लगेगा (पहले 18% था)।
    • 20 लीटर पैक्ड पानी, जैम-जैली, ड्राई फ्रूट्स और कन्फेक्शनरी आइटम्स भी 5% स्लैब में आ गए हैं।

    🧴 घरेलू और पर्सनल केयर प्रोडक्ट्स

    • टूथपेस्ट, टूथब्रश, शैम्पू, साबुन, टैल्कम पाउडर और हेयर ऑयल पर टैक्स 18% से घटाकर 5% कर दिया गया है।
    • किचनवेयर, टेबल-चेयर, साइकिल, छाता और घरेलू बर्तन भी 5% स्लैब में आ गए हैं।

    🏥 स्वास्थ्य सेवाओं और दवाओं पर राहत

    • सभी लाइफ इंश्योरेंस और हेल्थ इंश्योरेंस पॉलिसियां अब टैक्स फ्री होंगी।
    • 33 ज़रूरी और जीवन रक्षक दवाइयां (कैंसर की दवाइयां भी शामिल) को 0% GST में लाया गया है।
    • डायग्नोस्टिक किट, मेडिकल उपकरण, चश्मे और ग्लूकोमीटर जैसे प्रोडक्ट्स पर टैक्स 12% से घटकर 5% हो गया है।

    🚗 ऑटोमोबाइल सेक्टर और इलेक्ट्रॉनिक्स

    • पेट्रोल और डीज़ल की छोटी गाड़ियां (1200 cc तक पेट्रोल और 1500 cc तक डीज़ल) अब 18% स्लैब में होंगी (पहले 28%)।
    • मोटरसाइकिल 350cc तक, टीवी, एसी, डिशवॉशर, वॉशिंग मशीन भी 18% स्लैब में आ गए हैं।
    • इलेक्ट्रिक गाड़ियां (EVs) पहले की तरह 5% GST में रहेंगी।
    • बड़ी गाड़ियां, 350 cc से ऊपर की बाइक, यॉट और प्राइवेट एयरक्राफ्ट पर 40% टैक्स लगेगा।

    🏗️ रियल एस्टेट और इंफ्रास्ट्रक्चर

    • सीमेंट पर टैक्स 28% से घटाकर 18% कर दिया गया है।
    • स्टील और निर्माण सामग्री पर भी दरें घटाई गई हैं।
    • इससे हाउसिंग प्रोजेक्ट्स की लागत घटेगी और घर खरीदना आसान होगा।

    🌾 किसानों और कृषि उपकरणों के लिए राहत

    • खाद्य प्रसंस्करण मशीनें, चारा मशीन, सॉयल हार्वेस्टिंग मशीनें अब 5% स्लैब में।
    • प्राकृतिक मेंथॉल, बायो पेस्टिसाइड्स और ग्रेनाइट ब्लॉक्स पर टैक्स 12% से घटकर 5%।

    🚬 तंबाकू और पान मसाला पर सख़्ती

    • पान मसाला, गुटखा, सिगरेट और तंबाकू उत्पादों पर टैक्स 28% + 40% सेस लगेगा।
    • शुगर वाली कोल्ड ड्रिंक और एनर्जी ड्रिंक भी 40% टैक्स के दायरे में आएंगे।

    🗓️ नई दरें कब से लागू होंगी?

    नई जीएसटी दरें 22 सितंबर 2025 से, नवरात्रि के पहले दिन से लागू होंगी। GST rate cut: Everything from everyday items to vehicles becomes cheaper

  • आयकर से राहत को लेकर मोदी सरकार ने उठाया बड़ा कदम..

    आयकर से राहत को लेकर मोदी सरकार ने उठाया बड़ा कदम..

    • 7.27 लाख तक की आमदनी वालों को टैक्‍स नहीं।
    • अतिरिक्त 1 रुपये के लिए किस स्तर पर टैक्‍स का भुगतान करते हैं?
    • 50 हजार रुपये का स्‍टैंडर्ड ड‍िडक्‍शन।
    • मोदी सरकार का 2023-24 के लिए बजट में बढ़ोतरी।
    • आवंटन में करीब सात गुना की बढ़ोतरी।

    डिजिटल डेस्क (Indian fasttrack News Network)
    उडुपी
    में केंद्रीय वित्त मंत्री निर्मला सीतारमण ने कहा कि मोदी सरकार ने म‍िड‍िल क्‍लॉस को कई टैक्‍स बेन‍िफ‍िट प्रदान किए हैं। इसके तहत हर साल 7.27 लाख रुपये तक की आमदनी वालों को क‍िसी प्रकार का टैक्‍स नहीं देना होगा। उन्‍होंने कहा, सरकार ने समाज के किसी भी वर्ग को नहीं छोड़ा है। कुछ लोगों ने इस पर संदेह क‍िया, जब साल 2023-24 के केंद्रीय बजट में 7 लाख रुपये तक की आमदनी के ल‍िए आयकर छूट प्रदान करने का फैसला क‍िया गया था।

    7 लाख रुपये से ज्‍यादा की कमाई का क्या होगा?

    केंद्रीय वित्त मंत्री निर्मला सीतारमण ने यहां जानकारी देते हुए बताया, कि “लोगों को संदेह इस बात को लेकर था कि 7 लाख रुपये से ज्‍यादा की कमाई का क्या होगा? इसके बाद हम एक टीम के रूप में बैठे और ड‍िटेल में गए। हमने यह पता लगाया क‍ि आप प्रत्येक अतिरिक्त 1 रुपये के लिए किस स्तर पर टैक्‍स का भुगतान करते हैं। उदाहरण के लिए 7.27 लाख रुपये के लिए, अब आप क‍िसी प्रकार का टैक्‍स नहीं देते। केवल 27 हजार रुपये पर ही ब्रेक ईवन आता है। इसके बाद आप टैक्स देना शुरू करते हैं।”

    Indian fasttrack news
    मोदी सरकार,
    भारतीय अर्थव्यवस्था पर फाइल तस्वीर

    50 हजार रुपये का स्‍टैंडर्ड ड‍िडक्‍शन।

    न‍िर्मला सीतारमण ने कहा, “अब आपके पास 50 हजार रुपये का स्‍टैंडर्ड ड‍िडक्‍शन भी है। न्‍यू टैक्‍स र‍िजीम के तहत यह शिकायत थी कि कोई स्‍टैंडर्ड ड‍िडक्‍शन नहीं है। यह इस बार दिया गया है।” उन्होंने कहा, कि “हम भुगतान में सरलता लाए हैं।” सरकार की उपलब्धियों के बारे में बोलते हुए उन्होंने कहा, कि “सूक्ष्म, लघु और मध्यम उद्यमों (MSME) का कुल बजट 2013-14 के 3,185 करोड़ रुपये की तुलना में 2023-24 के लिए बढ़कर 22,138 करोड़ रुपये हो गया है।

    मोदी सरकार का बजटीय आवंटन में करीब सात गुना की बढ़ोतरी।

    उन्होंने कहा नौ साल के दौरान बजटीय आवंटन में करीब सात गुना की बढ़ोतरी हुई है। यह एमएसएमई (MSME) सेक्‍टर को सशक्त बनाने के लिए सरकार की अटूट प्रतिबद्धता का प्रतीक है। सूक्ष्म और लघु उद्यमों के लिए सार्वजनिक खरीद नीति योजना के तहत, 158 केंद्रीय सार्वजनिक क्षेत्र के उद्यमों द्वारा की गई कुल खरीद का 33 प्रतिशत एमएसएमई (MSME) से किया गया है। उन्होंने कहा, कि यह अब तक का सबसे ज्‍यादा आंकड़ा है।

    Live video on Indian fasttrack news channel

    दुन‍ियाभर में हुई भारत की तारीफ..

    उन्होंने कहा, “हमने टीआरईडीएस प्लेटफॉर्म (Trade Receivables Discounting System) लॉन्च किया। ताकि एमएसएमई (MSME) और अन्य निगमों को अपने खरीदार द्वारा भुगतान न करने के कारण ल‍िक्‍व‍िड‍िटी की कमी का सामना न करना पड़े।” सीतारमण ने कहा, कि “ओएनडीसी (ONDC) ने एमएसएमई (MSME) कारोबार को बड़े संभावित ग्राहक आधार तक पहुंचने में सक्षम बनाया है।” साथ ही उन्‍होंने कहा, क‍ि “दुनिया इस बात की तारीफ करती है, क‍ि भारत ने ब‍िजनेस सेक्‍टर के ल‍िए अच्‍छा काम क‍िया है।”

    उन्‍होंने यह भी बताया, क‍ि “व्यापार करना भारत में पहले से आसान हुआ है। वित्त मंत्री ने कहा, कि “ईज ऑफ डूइंग ब‍िजनेस इंडेक्‍स में भारत की रैंकिंग 2014 में 142 से बढ़कर 2019 में 63 हो गई है। हमने 1,500 से ज्‍यादा पुराने कानूनों और करीब 39 हजार अनुपालनों को निरस्त करके जरूरी अनुपालन बोझ को कम किया है।” उन्‍होंने कहा, कंपनी अधिनियम को अपराधमुक्त कर दिया गया है।